The One-Payment Effect: 70% of U.S. Adults Say Combining Debt Into One Payment Would Reduce Financial Stress
Keeping track of multiple debt payments is harder than it sounds. Even automatic payments can catch you off guard when they hit on different days of the month, draining your checking account when you least expect it.
How Does Debt Consolidation Affect Your Credit Score?
Credit utilization accounts for 30% of your FICO score — and debt consolidation can change it dramatically in either direction.
Debt Relief Programs: What They Are, How They Work, and When to Consider One
Understanding how debt relief programs work can help you find the right financial path when your debt becomes unmanageable — without jumping straight into bankruptcy.
Debt Snowball vs. Debt Avalanche: Which Payoff Method Is Right for You?
If you're juggling several balances and only a little extra cash each month, you've probably heard of two approaches: the debt snowball and the debt avalanche. One chases quick wins. The other chases the highest interest rate.
Does Debt Consolidation Work? 5 Signs You’ll Actually Stay Out of Debt
A growing pile of credit card bills isn't just about tracking debts, it's about watching interest pile up.
Debt Consolidation Loans Are at Record Highs—Should You Get One?
A debt consolidation loan can lower your interest costs and simplify repayment, but only if you consolidate the right debts at the right rate. Whether it's worth it depends on your APRs, repayment terms, and ability to stick to a budget.
Is Debt Consolidation a Good Idea? — Everything You Need to Know
If you're finding it difficult to meet minimum monthly payments for your credit cards or loans, simply cutting on monthly expenditures might not be enough.
Credit Union, Bank, or Online Lender? The Smartest Way to Consolidate Debt
Credit unions offer the lowest rates, banks offer convenience and larger loan amounts, and online lenders fund the fastest. Compare prequalified offers from more than one lender before deciding.
What Happens If You Default on a Debt Consolidation Loan?
Defaulting on a debt consolidation loan can seriously damage your credit score, trigger late fees, and put your assets at risk if the loan is secured. If you're struggling to keep up, contact your lender early, as deferment, restructuring, or credit counseling may help you avoid the worst outcomes.
How to Get a Debt Consolidation Loan in 6 Steps
Juggling multiple due dates while interest piles up is exactly the problem a debt consolidation loan is built to solve.
Is Debt Settlement a Good Idea? Risks and When It Makes Sense
Debt settlement can wipe out part of what you owe, but it damages your credit and can leave you with a tax bill. Here's how to tell whether it fits your situation.
What Is Debt Settlement and How Does It Work?
If you're juggling high balances and high-interest debt, you've probably wondered whether paying less than you owe is a real way out.
How to Consolidate Debt While Unemployed: 5 Options to Consider
Debt consolidation while unemployed is still possible when you stabilize cash flow first, document alternative income, and compare five lower-risk paths before you take on a new loan.
What Trump's Interest Cap Can Mean For Your Credit Card Debt
This announcement comes amid soaring credit card debt, which has reached approximately $1.166 trillion, and average interest rates that exceed 20%.
What Is Debt Consolidation and How Does It Work?
More Americans are turning to credit just to cover the basics, from groceries to utility bills, and as those balances stack up at high interest rates, consolidation is one way to make them more manageable.
Secured vs. Unsecured Debt Consolidation Loans
Consolidation loans offer a way to simplify your finances and make your debt more manageable.
Good Debt vs. Bad Debt: What’s the Difference?
Learn how good debt can build assets or income, how bad debt drains cash, and when borrowing lands in a gray area
Medical Bills Are Crushing Americans — How To Protect Your Credit
Medical debt has unique credit protections, but they disappear the moment you use a credit card or third-party financing. Know your options before you pay.
How Does a Home Equity Loan Work?
Home equity loans allow you to borrow up to 80% of your home's value at a fixed interest rate — typically lower than personal loans or credit cards because your home secures the debt. The average home equity loan rate as of early 2026 runs between 7%–9% depending on your credit score, loan term, and lender. Here's how they work, what they cost, and when they make financial sense.
Costs Are Rising - Here's How to Manage Your Spending
Costs of everyday expenses continue to rise — and it’s straining many Americans’ budgets.
7 States Where Foreclosures Are Spiking
The post-pandemic housing market is showing troubling signs as foreclosure numbers climb nationwide.
Do You Have Too Much Debt?
Debt can be a very useful strategy for reaching your financial goals. It can help you buy a home, start a business, or get an education. And you can use it to afford everyday purchases.
Should You Use a Home Equity Loan to Consolidate Debt?
Learn how tapping your home's equity can simplify payments and cut interest costs — plus the risks to weigh before you borrow against your biggest asset.
Can You Get a Second Debt Consolidation Loan?
Yes, you can get a second debt consolidation loan, but qualifying depends on your credit, income, and why the first one didn't finish the job.
What Self-Employed Workers Need to Know About Consolidating Debt — and Why Standard Advice Falls Short
When your paycheck goes up and down, it's harder to keep up with bills, and it's also harder to convince a lender you can pay one back on time.
Consolidated Your Debt, But Balances Are Back? Here's What To Do
Dealing with credit card debt after consolidation can feel incredibly isolating, frustrating, and exhausting. You took the responsible step of lowering your interest rates and streamlining your payments, so why did the balances return?
JG Wentworth vs. National Debt Relief: Which Debt Settlement Program Fits You?
If you’re struggling to pay down your credit cards or other debt and don’t want to take out any more loans, a debt settlement program could provide you with some relief.
Balancing Household Debt in a High-Interest Economy: 5 Tips for 2026
In 2026's high-interest economy, the difference between financial struggle and success lies in how you manage household debt.
Debt Management vs. Debt Consolidation: Which is Better?
Feeling overwhelmed by debt? Whether you're dealing with maxed-out credit cards or juggling multiple payments, understanding your options is key. This guide compares debt management vs. debt consolidation — two leading strategies for how to get out of debt in 2026. We'll break down the pros, cons, and ideal use cases for each approach.
Debt Consolidation Loans: Should You Apply Now or Wait for the Fed to Cut Interest Rates?
Navigating the 2026 credit market requires balancing the urgency of high-interest debt against the promise of shifting Federal Reserve policies.
Credit Score Ranges: What They Mean and How They Work (2026)
Your credit score affects everything from loan approvals to the interest rates you pay — and understanding where you fall on the scale is the first step toward better financial decisions.
Debt Collectors: What They Can and Cannot Do
Debt collectors have to follow federal rules, and knowing them helps you respond with confidence instead of pressure. This guide covers what collectors can and can't do, how debt validation works, and when to escalate a violation.
Cosigner for a Debt Consolidation Loan: What You Need to Know
A cosigner with strong credit can help you qualify for a debt consolidation loan or a better rate, but they take on real legal responsibility if you fall behind.
Balancing the Bills: How to Navigate Debt Consolidation While Unemployed
This guide breaks down how lenders evaluate unemployed borrowers, which consolidation options may work, and when hardship programs or credit counseling are the safer choice instead.
How to Pay Off Debt in 2026
Paying off debt has short-term and long-lasting benefits for your finances. You can reduce your monthly bills, putting more money back in your pocket. You can simplify your financial picture by reducing the bill payments you must manage. And you can save hundreds, or even thousands, of dollars in interest.
Buy Now, Pay Later Debt Consolidation: What to Do When BNPL Balances Start to Multiply
BNPL balances pile up fast, and nearly one in four users fall behind on payments as a result. Consolidating with a personal loan, balance-transfer card, or debt management plan can simplify multiple due dates into one manageable payment.
Debt Consolidation vs. Credit Counseling
If you're carrying more debt than you can comfortably manage, you're not alone — and you have real options. Debt consolidation and credit counseling are two of the most common paths forward, but they work in fundamentally different ways, and choosing wrong can cost you thousands
Medical Debt Consolidation: What It Is and How to Do It
Medical bills from various sources—credit cards, lenders, family, friends, or collection agencies—can quickly become overwhelming.
What’s the Difference Between Debt Consolidation and Debt Settlement?
Struggling with multiple debts? Understanding the difference between debt consolidation and debt settlement is crucial for managing your financial future. Let's explore these two debt management strategies to help you make an informed decision.
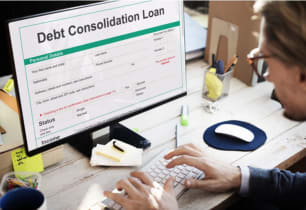
How To Choose the Right Debt Consolidation Loan
Having debt can be stressful. Especially when that debt is spread out across a variety of credit cards, personal loans, medical bills, and more. Often, the right course of action is to get a debt consolidation loan and bundle everything into one low monthly payment. In this article, I’m going to outline some of the top things to consider when choosing a debt consolidation loan.
What Is a Debt Management Plan (DMP)?
If keeping up with debt payments feels like you’re swimming against the current, a debt management plan (DMP) may offer a structured path to a debt-free life.
Best Debt Consolidation Loans for Fair Credit
Our top picks — Freedom Debt Relief, Upgrade, and Discover Personal Loans — were selected after evaluating lenders and debt relief providers on credit score accessibility, APR competitiveness, fee transparency, and real-world fit for fair-credit borrowers
Best Debt Consolidation Loans for Bad Credit in 2026
Struggling to keep up with multiple high-interest debt payments can feel overwhelming, but having bad credit doesn't mean you're out of options.
How to Consolidate Payday Loans: A Step-by-Step Guide
Payday loans offer quick cash when you're in a financial bind, but they come with significant drawbacks.
States With the Most Consumer Bankruptcies
More than 500,000 Americans filed for consumer bankruptcy in fiscal year 2025, reflecting continued financial pressure on households across the country. But the burden is not spread evenly: filings are concentrated in certain states, revealing where consumers may be facing the greatest financial strain.
The Risks of Using Your 401(k) to Consolidate Debt
Before you tap your retirement savings to pay off debt, understand the penalties, tax consequences, and long-term costs — plus smarter alternatives.
How to Calculate Your Debt Consolidation Loan Savings
Debt consolidation loans are personal loans that combine multiple debts into a single loan with a fixed interest rate. They can save you money on interest if your loan has a lower APR than what you’re currently paying.
Accredited Debt Relief vs. National Debt Relief: Which Debt Settlement Company Is Better?
Accredited Debt Relief and National Debt Relief are two of the most popular debt settlement options on the market. They can negotiate down the amounts you owe to your creditors, then manage your payments while you work to pay off your debts.
Student Loan Refinancing vs. Consolidation: Which Is Right for You?
Do you have hefty student loans that you’re still working on repaying? Are you wondering if there’s a smarter way you could be repaying them, either through refinancing or consolidation?
Is a Debt Consolidation Loan Right for Your Credit Card Debt?
Learn how combining multiple credit card balances into one loan could lower your interest rate and simplify your monthly payments.
Debt Consolidation vs. Balance Transfer Card: Which Option Is Better?
Both paths can simplify your payments and cut interest costs — but the right choice depends on how much you owe, your credit profile, and how fast you can pay it off. Backed by 50+ financial experts, 3,000+ hours researched, 100+ comparison tools, calculators & more.
How to Consolidate Credit Card Debt: A Guide to Simplifying Payments
Paying five credit cards at five different interest rates every month is expensive — and stressful. Credit card debt consolidation replaces that tangle with one loan, one rate, and one monthly payment. The result: less interest, fewer deadlines, and a faster path out of debt.
Should Couples Get Joint Debt Consolidation Loans? Pros, Cons, and How They Work
A joint debt consolidation loan lets couples combine multiple debts into one payment, but ties both partners' credit and finances together. Before applying, ensure you're aligned on repayment expectations, fully transparent about your finances, and prepared for worst-case scenarios.
Can You Pay Off a Debt Consolidation Loan Early? What to Know About Prepayment Penalties
Paying off a debt consolidation loan early can reduce your total interest, but only makes sense if your lender doesn't charge steep prepayment penalties. Before making extra payments, weigh the savings against other financial priorities like emergency savings and retirement contributions.
Debt-to-Income (DTI) Calculator
Your Debt-to-Income (DTI) ratio is a personal finance measure that compares your total monthly debt payments to your gross monthly income. In simple terms, it tells you exactly what percentage of your paycheck goes toward paying off what you owe before taxes are taken out.
How to Get Out of Debt Fast in 2026: A Step-by-Step Guide
Debt consolidation can help some borrowers pay off debt faster by combining their debts, simplifying their monthly payments, and even saving money on interest.
What to Do If You're Denied for a Debt Consolidation Loan
A denial usually points to low credit, high DTI, or unstable income. Your next steps depend on the cause, from credit repair to debt management plans or balance transfers.
What Is a Debt-to-Income Ratio and How Do You Calculate It?
Your DTI compares monthly debt payments to gross income, and lenders want it at 36% or below. Pay down revolving debt or boost income to improve your ratio before applying for a loan.
Debt Consolidation vs. Bankruptcy
American households carry a staggering $17.94 trillion in total debt, with credit card balances reaching $1.17 trillion. If you're among the millions feeling the weight of debt, understanding your relief options is crucial.
How to Pay Off Wedding Debt
The average wedding costs $34,200, and financing it the wrong way can burden your marriage from day one. Learn which options make sense, which to avoid, and how to consolidate any debt you're left with after the big day.
10 Ways to Rebuild Credit
When your credit isn't in the best shape, reaching your financial goals becomes significantly more challenging. You'll face difficulties getting approved for credit, and might also miss out on the best interest rates available. It might even prevent you from landing certain jobs or renting the home you want.
What Is My Credit Score if I Have No Credit History?
When you have no credit history, you also have no credit score. This happens because there's simply no information available to create a credit report or calculate a score, either because you've never used credit before or haven't used it in a very long time.
Survey: Millennials and Gen X Are Saving More — But Debt Levels Continue to Rise
Millennials and Gen X are doing what personal finance experts recommend: saving regularly. But for many, that is not keeping them out of debt.
Risk or Reward: Should Retirees Tap Home Equity to Pay Off Debt?
Retirees with strong equity and high-interest debt may benefit from tapping home equity, but the risks are real. Weigh your income, longevity, and estate plans before borrowing.
Freedom Debt Relief vs. National Debt Relief: Which Debt Settlement Company Is Better in 2026?
Both companies offer similar debt settlement services, but National Debt Relief edges ahead on customer satisfaction while Freedom Debt Relief leads on scale and digital tools.
America’s Most Frugal Cities: Where Savvy Spending Shapes Everyday Life
Frugality isn’t just about clipping coupons or skipping your morning latte—it’s a mindset. And in a world where prices seem to rise faster than paychecks, more Americans are embracing this intentional way of spending.
Our Methodology:
We’ve created the following process to identify the most suitable debt consolidation companies for your needs and deliver on our mission to help you make informed decisions.